You’re Turning Over $2 Million — So Where Is the Profit? | SCS Performance
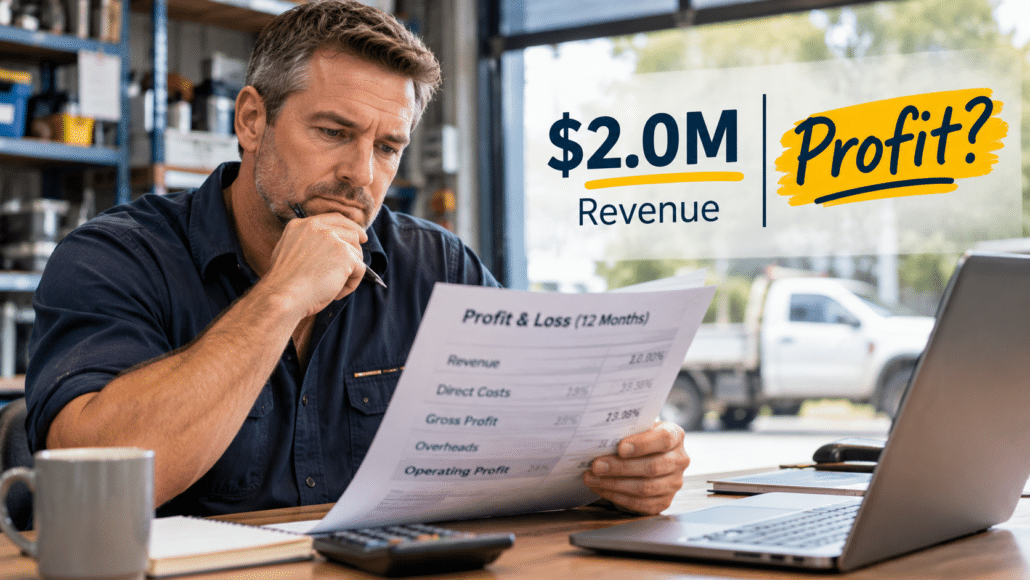
A $2 million turnover sounds impressive. But if there isn’t enough profit or cash left at the end of the year, turnover is little more than a big number.
Your business is busy. You employ a team. The phones are ringing. Suppliers know you. Customers keep coming back. Your accountant tells you revenue has increased again.
On the surface, things look pretty good.
But there is a more important question:
How much money are you actually keeping from that $2 million?
This is something we regularly see in established trade, service and allied-health businesses. Turnover has grown, but somewhere along the way the financial return to the owner hasn’t kept pace.
The business has become bigger, busier and more complicated — but not more profitable.
Turnover is only the starting point
Revenue matters as you can’t make profit without it, but by itself it tells you very little about the financial performance of your business.
From every dollar of sales you may need to pay direct labour, materials, subcontractors, superannuation and other employment costs, vehicles, rent, insurance, administration, software, finance costs and dozens of other expenses.
What remains after paying those costs is what really matters.
Consider two businesses, each turning over $2 million.
Business A
$2,000,000 revenue × 6% operating profit = $120,000 profit
Business B
$2,000,000 revenue × 12% operating profit = $240,000 profit
Exactly the same turnover.
But one produces twice the financial return.
This is why chasing more revenue isn’t automatically the answer to a profit problem. In some cases, adding more work to a poorly performing business simply creates more work, more pressure and more stress.
Before chasing another $200,000 of sales, understand what is happening to the $2 million you already have.
Where is the money going?
If your business is busy but isn’t producing the profit you expect, I would initially look at five numbers.
1. Gross profit percentage (also know as Gross Margin)
Your gross profit is what remains after the direct costs associated with delivering your products or services.
If your gross profit percentage is declining, investigate why.
Have supplier costs increased? Are labour hours blowing out? Are you discounting? Are materials being missed on invoices? Is rework increasing? Are jobs being quoted using old cost assumptions? Are you invoicing everything?
A small movement can have a surprisingly large impact.
2. Labour cost and recovery
For labour-intensive businesses, labour is typically the biggest potential profit leak.
An employee’s hourly wage isn’t their true hourly cost.
You also need to consider superannuation, WorkCover, leave, downtime and other employment costs — and then understand how many genuinely productive or recoverable hours that employee generates.
If you don’t know what an hour of labour actually costs you, setting a profitable charge-out rate becomes very difficult.
3. Overhead percentage
Growing businesses have a habit of accumulating overheads.
Another administrator. Another vehicle. Another software subscription. Bigger premises. More insurance. Another manager.
Individually, each decision may be completely reasonable.
Collectively, they can consume a significant amount of your gross profit.
The question isn’t simply whether an expense is useful. The better question is: what return is the business getting from it?
4. Operating profit
Eventually everything reaches the bottom line.
After paying the costs of operating the business, what is actually left?
And is that amount adequate compensation for the capital you have invested, the financial risk you carry and the time and effort required from you as the owner?
A business generating $100,000 of profit isn’t necessarily performing well simply because $100,000 sounds like a reasonable amount. It needs to be considered against the size, risks and demands of the business producing it.
5. Cash generation
Profit and cash are related, but they aren’t the same thing.
A profitable business can still be desperately short of cash because money is tied up in debtors, work in progress or inventory, or is being absorbed by loan repayments, tax liabilities and other working-capital requirements.
That is why we look at profit and cash together.
Small percentages can mean big dollars
One of the simplest financial exercises for a business owner is converting percentages into actual dollars.
Suppose your business turns over $2 million and historically achieves a 35% gross profit margin.
$2,000,000 × 35% = $700,000 gross profit
Now assume material increases, labour inefficiencies and poor cost recovery reduce your margin to 32%.
$2,000,000 × 32% = $640,000 gross profit
That’s a difference of:
$700,000 − $640,000 = $60,000
Nothing catastrophic necessarily happened.
Customers didn’t disappear. Revenue didn’t collapse. The team may be busier than ever.
But three percentage points just cost the business $60,000.
That is why even small movements on your Profit & Loss deserve attention.
Profit usually disappears a little at a time
In our experience, there is rarely one enormous problem responsible for poor profitability.
More commonly, we find numerous smaller issues.
Prices haven’t kept pace with costs. Employees spend too much time on non-productive work. Materials aren’t fully recovered. Quotes are discounted unnecessarily. Jobs run over their allocated hours. Rework has increased. Overheads have crept upwards. Nobody is regularly comparing estimated versus actual job performance.
One issue might be worth $10,000.
Another $15,000.
Another $20,000.
Find five or six of them and suddenly there can be $100,000 or more disappearing from the business.
The good news is that this also means profit improvement doesn’t necessarily require one enormous change.
What should you do Monday morning?
Start by looking backwards before chasing more sales.
Take your latest 12-month Profit & Loss statement and compare it with the previous 12 months.
Don’t start with turnover.
Look at:
-
Gross profit percentage
-
Wages as a percentage of revenue
-
Overheads as a percentage of gross profit
-
Operating profit
-
The major expenses that have materially increased
Then identify the three biggest negative movements and convert each one into dollars.
From there, build an improvement plan.
For example:
2% improvement in GP on $2 million revenue = $40,000
Overhead savings = $15,000
Improved labour productivity/recovery = $30,000
Potential annual profit improvement = $85,000
That is a much more useful business objective than simply saying, “We need more sales.”
A bigger business isn’t automatically a better business
For most owners, the objective shouldn’t be turnover for turnover’s sake.
It should be building a business that produces an appropriate financial return, doesn’t consume every available hour of your week and doesn’t create unnecessary financial stress.
Sometimes increasing sales is absolutely the answer.
Sometimes the better answer is improving the performance of the revenue you already have.
If your turnover looks healthy but you’re wondering where the profit is going, SCS Performance can help you find out.
Our complimentary Strategy Session gives you 60 minutes to put the numbers and your biggest business frustration on the table. We’ll work through what’s happening, identify where the opportunities may sit and give you a clearer view of what to do next.
Your business should pay you back.
Book your complimentary SCS Performance Strategy Session and let’s find out where the money is going.

Leave a Reply
Want to join the discussion?Feel free to contribute!